Tarped in 2–4 hours · documented for your insurer · answered 24/7
Roof Damage in Houston: What To Do First
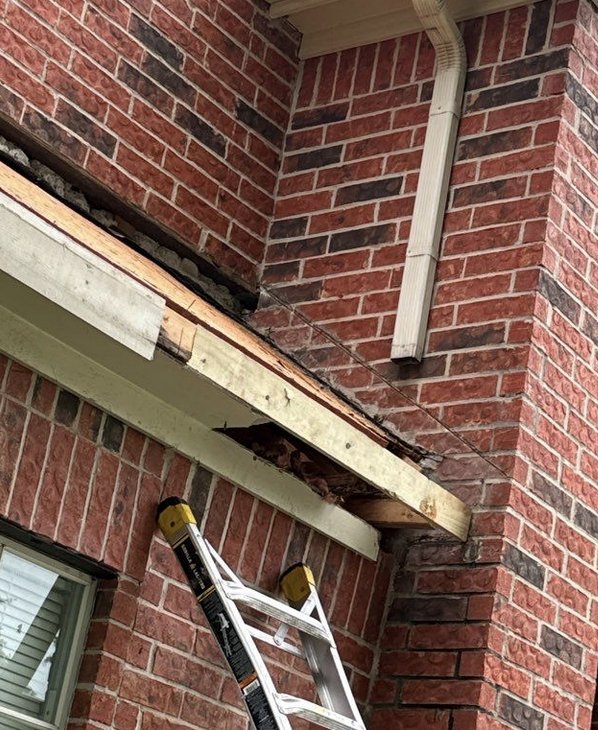
Roof damage in Houston after a storm? This page is written in the order things actually need doing — the first hour, the first day, then the claim. We tarp within 2 to 4 hours to stop water getting in, document the roof damage for your insurer while the evidence is fresh, and meet your adjuster on the roof.
Not sure what hit you? Hail, wind and hurricane damage look different and are assessed differently. The damage guide below sorts it out in about a minute, then sends you to the full checklist for whichever one you have.
If water is coming in right now
(713) 766-3464 713-ROOFING · Tomball & northwest (281) 498-7663 281-498-ROOF · Houston & inner loop- Tarped first, repaired properly after. Stopping the water comes before anything else.
- Documented slope by slope. Photographs dated close to the storm are what a fair insurance claim is built on.
- Wind damage starts at the edges. Ridge cap, rake and starter strip — the three courses most often cut short on installation.
- We meet your adjuster on the roof, so both parties are looking at the same damage.
- We will tell you if you have no claim. Filing one you will lose can count against you.
- Replaced with a Class 4 roof. Timberline UHDZ carries the highest UL 2218 impact rating — built for the hail that took the last one.
Second, work out what hit you
Which Kind of Roof Damage Do You Have?
It matters more than it sounds. The three kinds of roof damage in Houston a storm leaves behind look different, get assessed differently, and in Texas are not always covered under the same deductible. Each has its own page with the full checklist.
If there was hail
Hail damage
- Bruises rather than punctures, so it often does not leak for months
- Granules collecting at the bottom of downspouts
- Dents in soft metal — vents, flashing, the mailbox, AC fins
Hail damage roof repair →
If it was a straight-line blow
Wind damage
- Fails at the edges first — ridge cap, rake, starter strip
- Shingles standing proud of the course below, or a ridge line gone crooked
- Shingles in the yard or the flower beds
Wind damage roof repair →
If it was a named storm
Hurricane damage
- Your hurricane deductible is usually a percentage, not a flat sum
- Wind and water damage are often treated separately by the policy
- Whether filing at all is the right call is a real question
Hurricane roof damage →
Water is coming in right now
Then this is an emergency call, not a research job. Tarping first to stop the water, proper repair once the roof is dry. Answered 24 hours a day, from $150.
Emergency roof repair →
You need to know what you actually have
Every slope photographed, attic checked where there is access, and a written report whether or not you file — and whether or not you use us. No hammers, just chalk and a camera.
Book a free roof inspection →
You want to understand the claim itself
Three deductibles, two deadlines, and the difference between actual cash value and replacement cost — before you phone your insurer.
How Texas roof claims work →
When a claim is approved
Your Insurer Pays for the Roof You Had. We Build a Better One.
A settlement covers replacing what was there. It does not decide which contractor installs it, which shingle goes on, or what warranty you are left holding — and those are the parts that matter for the next thirty years.
What we register on an approved claim
GAF Golden Pledge with Timberline UHDZ
Not an upgrade we sell you. What we register, as standard, on every approved claim.
- Class 4 impact resistance. UHDZ carries a UL 2218 Class 4 rating, the highest of the four classes — so the replacement is built for what took the last one.
- 30 years of workmanship, backed by GAF. Non-prorated, and covered by the manufacturer rather than resting on whether a contractor is still trading. Silver Pledge, by comparison, carries 10.
- 50-year non-prorated protection period. The window in which coverage is not reduced by age.
- No wind speed cap. WindProven carries no maximum wind speed limitation on LayerLock-labelled shingles — the number worth having on the Gulf Coast.
- Ventilation corrected and pivot pipe boots fitted on every claim replacement, whether or not the scope asks for them.
Why most contractors cannot offer this. Golden Pledge requires a GAF Master Elite contractor — roughly 2% of US roofers — installing five qualifying accessory products as a system. It cannot be added to a quote. Ask any contractor bidding your claim which pledge they register and which shingle it applies to. The full system, shingle by shingle · What UL 2218 and the Texas credit mean
Terms are GAF’s and subject to their published limitations. Class 4 applies to UHDZ shingles bearing the UltraMat logo and UL 2218 classification; the test is performed under controlled laboratory conditions and GAF makes no warranty about performance against hail, which is not covered by the limited warranty. The Texas Department of Insurance states that a Class 4 roof covering receives the highest premium credit of the four classes; the amount is set by each insurer, not by the state, and is never applied automatically. Full comparison at gaf.com.
What happens next
From Your Call to a Finished Roof
You file the insurance claim. We handle the storm damage and the evidence the claim runs on.
-
We stop the water
Typical response 2 to 4 hours, any day of the year. Tarping and emergency measures come first — every hour water is entering makes the interior damage worse and the claim more complicated.
-
Full inspection, documented slope by slope
Every elevation photographed, damage marked, decking and flashing assessed, attic checked where there is access. You get the photographs and a written summary whether or not you file, and whether or not you use us.
-
You report it to your insurer
You make that call — a contractor cannot file on your behalf. Our documentation means you are describing something specific rather than guessing. What to say when you call.
-
We meet your adjuster on the roof
So both parties assess the same damage at the same time, from the same vantage point. Most scope disputes come from two people looking at a roof separately and reaching different conclusions.
-
You compare the scope to our estimate
If the insurer’s scope is missing items — decking, code upgrades, flashing quantities — we document the gap so you can submit a supplement. That is common and normal.
-
We build the roof
Golden Pledge system with Timberline UHDZ, registered with GAF on completion. Final inspection, magnet sweep, and the paperwork you need to release your recoverable depreciation.


Where we stop
We are roofers, not public adjusters. We do not file insurance claims, negotiate settlements, or represent you to your insurer — in Texas that work is reserved to licensed public adjusters, and a roofer offering to do it is offering something they are not licensed for.
What we do is produce documentation good enough that the claim is judged on what is actually on your roof. That is the part we control, and it is the part that matters.
Paying the deductible
Claim Approved, Deductible in the Way?
The most common reason an approved roof insurance claim stalls. The insurer has agreed to pay, the roof needs doing, and the deductible — often $2,000 to $5,000, or a percentage of your dwelling coverage — is not sitting in the account this month.
It can be financed like any other roofing cost, which lets the work start while the claim proceeds. Three plans, with the real terms:
- Wells Fargo — 18 months same as cash. Clear the balance inside 18 months and you pay no interest. If any of it is still outstanding at 18 months, interest at 28.99% is charged back to the first day. This is deferred interest, not 0% APR, and the difference matters.
- Wells Fargo — fixed rate. 8.99% APR over 70 months, no deferred interest and no cliff.
- Service Finance, a Truist company. 9.99% over 120 or 180 months, or six months of no payments followed by 120.
All financing is through the Wells Fargo Home Projects credit card issued by Wells Fargo Bank, N.A. or through Service Finance Company, and all of it is subject to credit approval. Terms are set by the lender and can change.
To be clear about what this is. Texas law prohibits a roofing contractor from paying, waiving, absorbing or rebating a homeowner’s insurance deductible. Any contractor offering to “cover your deductible” or “work with whatever insurance pays” is proposing something illegal, and it puts your claim at risk as well as theirs.
Financing is different: you pay your deductible in full, over time rather than at once. That is an ordinary consumer credit arrangement.
Common questions
Houston Roof Damage Questions, Answered
How fast can you get here?
Typically 2 to 4 hours, 24 hours a day, 365 days a year. After a major storm that stretches — when thousands of roofs are damaged at once, everybody’s does.
We prioritize active water intrusion. If it is raining into your house, say so when you call.
My roof looks fine. Could it still be damaged?
Frequently, yes. Wind can break a shingle’s seal strip without moving it, and impact damage bruises rather than punctures — so a roof hit in April can look untouched from the driveway and start leaking in October.
From the ground: granules in the gutters, dents on soft metal such as vents, flashing, the mailbox and air-conditioning fins, and any shingle standing proud of the course below. If you think it was hail specifically, the full checklist is on the hail damage page.
Should I file an insurance claim?
Not always. If the damage is close to your deductible, filing may cost you more in premium and claims history than it returns.
We will inspect and tell you honestly what we find, including when our answer is that you probably do not have a claim worth filing. A contractor who encourages every homeowner to file is not looking after your interests.
Do you handle the claim for me?
No. Filing, negotiating and settling a claim is the work of a licensed public adjuster, and in Texas a roofer cannot do it. Anyone who offers to is offering something they are not licensed for.
What we do: inspect, document slope by slope, produce an itemised scope, and meet your adjuster on the roof. How the process works.
What if the insurer’s payment does not cover the work?
Common, and it has a name — a supplement. Adjusters work from one visit and a standard pricing database, so decking, code upgrades and flashing quantities are often missed.
We document the gap so you can submit it. What we will not do is quietly cut scope to fit the check — that is how a roof ends up without its leak barrier.
I have 3-tab shingles. What do I get?
A Class 3 impact-resistant shingle — a substantial step up from 3-tab, which carries no meaningful impact rating. Homes that had architectural shingles get Class 4 Timberline UHDZ.
Either way, nobody gets put back on the shingle that just failed. We also upgrade the ventilation on every replacement — fitting O’Hagin low-profile intake vents where a house has no soffit venting or the insulation is blocking it — and fit GAF Master Flow pivot pipe boots, since pipe penetrations are among the most common places a roof starts leaking.
Why UHDZ rather than another Class 4 shingle?
There are two ways a shingle reaches Class 4. One blends a polymer into the asphalt — SBS-modified — so it stays pliable and deforms under impact instead of cracking. The other reinforces the shingle’s core with a heavier fiberglass mat, which is how UHDZ does it.
Both earn the rating. But in our experience on Houston roofs, SBS-modified shingles are more prone to blistering in sustained heat, and we stopped installing them for that reason. UltraMat gets the same Class 4 rating without a pliable asphalt layer to blister when an attic runs at 140°F.
Which warranty do I get on an insurance job?
GAF Golden Pledge with Timberline UHDZ — lifetime shingle coverage, a 50-year non-prorated protection period, and 30 years of non-prorated workmanship coverage backed by GAF, not just by us.
Golden Pledge can only be registered by a GAF Master Elite contractor installing five qualifying accessory products. Ask any contractor bidding your claim which pledge they register.
UHDZ also carries a UL 2218 Class 4 impact rating — the highest of the four classes — which matters when most Houston claims are hail claims. It also attracts the highest insurance credit of the four classes, though how much is set by your carrier rather than the state. What UL 2218 and the Texas discount actually mean.
What does wind damage to a roof actually look like?
Wind does not lift a roof evenly. It fails at the edges — the ridge cap, the rake and the starter strip along the eaves, which are the three courses most often cut short or under-nailed on installation.
From the ground, look for shingles standing proud of the course below, a ridge line that is no longer straight, granule piles at the downspouts, and shingles in the yard or the flower beds. A shingle that lifted and laid back down has broken its seal strip even though it looks fine, and it will lift again in the next storm.
Will insurance cover wind damage if the roof is old?
Often yes, but how much depends on your policy. Many Texas policies pay actual cash value on an older roof rather than replacement cost, which means depreciation comes off the settlement. Some carriers apply a roof-payment schedule that reduces the payout by the roof’s age regardless.
Age is not by itself a reason not to file — wind damage is wind damage. It is a reason to know which basis your policy uses before you call, which is on the claims page.
Before you let anyone on your roof
Roof damage brings contractors to Houston who will not be here next year. Check whoever you are considering — including us.




Damage now? Call.
Free inspection for roof damage in Houston, with photographs of everything we find — whether or not you file, and whether or not you use us.
JC&C Roofing Company ·
1431 Graham Dr #266, Tomball, TX 77375 ·
1220 Blalock Rd #345, Houston, TX 77055
hello@jccroofing.com ·
Text (832) 590-3700 · answered 24/7